Table of Contents
Key Takeaways
- The VA loan benefit offers significant upfront cost advantages and no PMI for eligible buyers with full entitlement, subject to lender underwriting and qualification requirements. Conventional loans generally require both upfront cash and PMI when equity is below 20%.
- The VA funding fee is a one-time cost that varies based on loan type and use of the benefit. Buyers with a service-connected disability may be exempt entirely.
- Conventional loans are the better fit for investment properties, second homes, or buyers with substantial savings who want to avoid the funding fee.
- San Diego’s 2026 conforming limit is $1,104,000. VA-eligible buyers with full entitlement face no county loan cap.
- Which loan is right for you depends on your financial situation, property type, and long-term plans. A lender can run both scenarios with your actual numbers.
If you are VA-eligible and buying in San Diego, the comparison between a VA loan and a conventional loan comes down to a few specific factors: your upfront financial situation, what type of property you are buying, and what your long-term plans are. For most VA-eligible buyers purchasing a primary residence, the VA loan offers structural advantages that conventional loans cannot match. But conventional can be the right call in specific situations.
This guide breaks down the key differences between the two loan types so you can have a more informed conversation with a lender before you decide.
The Core Difference Between VA and Conventional Loans
A VA loan is a mortgage backed by the U.S. Department of Veterans Affairs, available to eligible active duty service members, veterans, and qualifying surviving spouses. The VA guarantees a portion of the loan, which allows approved lenders to offer terms that would not be possible through a standard conventional loan.
A conventional loan is a mortgage not backed by a government agency. It follows guidelines set by Fannie Mae and Freddie Mac and is available to any qualifying borrower, regardless of military service. Conventional loans are the most common mortgage product in the country.
The most meaningful structural difference: VA loans offer significant upfront cost advantages and no PMI for eligible buyers. Conventional loans generally require both upfront cash and PMI until equity reaches 20%.
Where VA Loans Have a Structural Advantage
Significant upfront cost advantages with full entitlement
The VA loan benefit offers significant upfront cost advantages for eligible buyers with full VA entitlement, subject to lender underwriting and qualification requirements. In San Diego, where median home prices sit around $900,000, that represents a meaningful financial advantage for qualifying buyers compared to conventional loan requirements.
No private mortgage insurance
VA loans never require private mortgage insurance (PMI), regardless of how much you put toward the purchase. PMI on a conventional loan adds to your monthly payment until you reach sufficient equity. VA buyers avoid this cost entirely.
No county loan cap with full entitlement
Since 2020, VA loans have had no county-level loan limit for buyers with full entitlement. Eligible borrowers with full entitlement may be able to finance above the 2026 San Diego conforming limit of $1,104,000, subject to lender underwriting and qualification requirements. A conventional buyer above that limit enters jumbo territory, which typically requires stronger reserves and stricter qualification standards.
No loan-level price adjustments
Conventional loans use loan-level price adjustments (LLPAs), pricing additions tied to your credit score and equity position. VA loans do not use LLPAs the same way, making VA more accessible for buyers who would face significant pricing penalties on a conventional loan.
More flexible credit standards
The VA sets no minimum credit score. Lenders apply their own standards, but VA loans are generally more forgiving of past credit challenges than conventional loans.
Where Conventional Loans Have an Advantage
Investment properties and second homes
VA loans are for primary residences only. For rental properties, vacation homes, or second homes, a conventional loan is the only path.
Buyers with substantial savings
For buyers who can bring substantial cash to closing, a conventional loan can eliminate both PMI and the VA funding fee. For well-qualified buyers in that position, conventional may be more competitive. A lender can run both scenarios with your actual numbers.
Property condition flexibility
VA loans require properties to meet VA Minimum Property Requirements (MPRs). A fixer-upper needing significant repairs may not pass a VA appraisal. For buyers targeting properties that need work, conventional financing may be more practical.
PMI can be removed
On a conventional loan, PMI is not permanent. At 78% LTV based on the original purchase price, the lender is required by law to cancel it automatically under the Homeowners Protection Act. For buyers who plan to pay down aggressively or expect strong appreciation, this eventual PMI removal reduces long-term cost.
Understanding the VA Funding Fee vs PMI
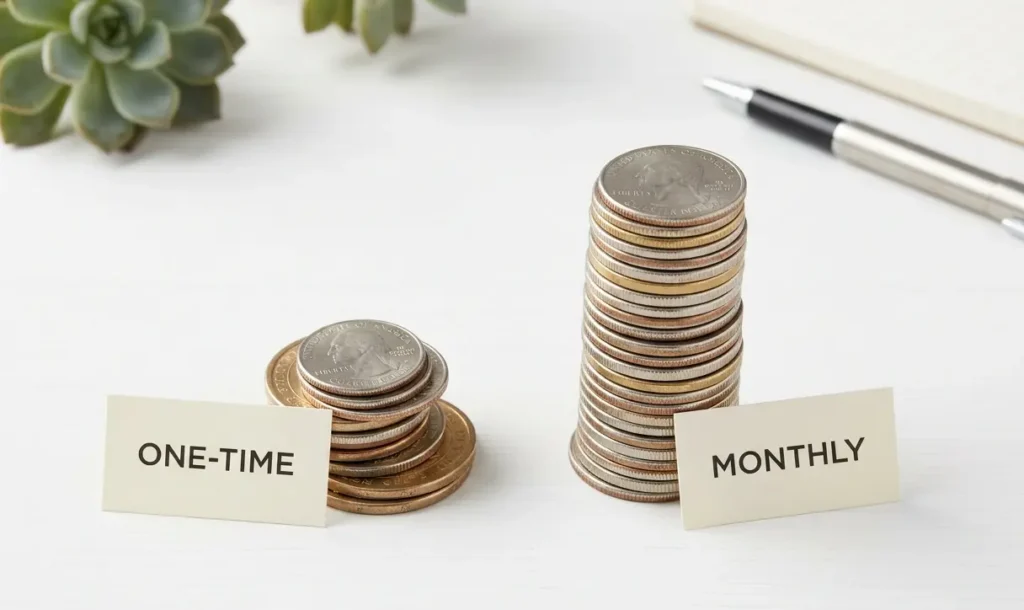
The most common cost comparison between VA and conventional loans comes down to the VA funding fee versus private mortgage insurance. According to the Consumer Financial Protection Bureau, PMI is paid monthly until the loan reaches 80% loan-to-value. On a large San Diego loan, that can add up to a meaningful ongoing cost over many years.
The VA funding fee, by contrast, is a one-time cost. The fee varies based on your loan type and whether this is your first or subsequent use of the benefit. It can be rolled into the loan balance rather than paid out of pocket at closing. Buyers with a service-connected disability rating, certain surviving spouses, and Purple Heart recipients on active duty are generally exempt from the funding fee entirely.
For buyers comparing the two loan types, the relevant question is which structure produces a lower total cost over the time you plan to hold the loan. That calculation depends on your specific loan amount, credit profile, and how long you expect to own the home. A lender can run both scenarios with your actual numbers.
What About the Loan Limit in San Diego?
According to the Federal Housing Finance Agency, the 2026 conforming loan limit for San Diego County is $1,104,000. This is the maximum loan amount eligible for standard conventional financing through Fannie Mae and Freddie Mac. Above that limit, conventional borrowers enter jumbo territory, which typically requires stronger reserves and stricter income documentation.
VA loans work differently. Eligible buyers with full entitlement face no county-level loan cap. A VA-eligible buyer purchasing above the conforming limit can still apply for VA financing with significant upfront cost advantages, subject to lender underwriting and qualification requirements. A conventional buyer at the same price point would need to meet jumbo qualification standards.
For San Diego buyers at or above the conforming limit, this difference is significant. It is one of the reasons the VA loan carries particular weight in higher-priced corridors near MCAS Miramar and Naval Base San Diego.
Which Loan Is Right for You in San Diego?
The answer depends on your specific situation. Here are three common buyer profiles to illustrate how the decision might play out. These are for illustrative purposes only and are not a substitute for a conversation with a lender about your actual numbers.
Profile 1: VA-eligible buyer with limited upfront cash
For most buyers in this position, the VA loan provides clear structural advantages: significant upfront cost advantages, no PMI, and no loan cap. The one-time funding fee is generally lower in total cost than years of monthly PMI, particularly in San Diego where loan amounts are large. This is the scenario where VA tends to be the stronger fit for most buyers, subject to lender underwriting and qualification requirements.
Profile 2: VA-eligible buyer with substantial savings and strong credit
With substantial savings, the comparison is less one-sided. A conventional loan can eliminate both PMI and the VA funding fee. Both options are worth running with a lender. The deciding factors often come down to property type and whether a funding fee exemption applies.
Profile 3: Buyer purchasing a fixer-upper or investment property
For an investment property, conventional is the only path since VA loans require primary residence occupancy. For a property that needs significant repairs before it would pass a VA appraisal, conventional may also be the practical choice. These are the clearest cases where a VA-eligible buyer might still choose conventional.
For a full overview of the VA loan benefit and how it works in San Diego, visit Maureen’s VA loan page. To check your VA eligibility, visit sandiegohomelender.com/qualify-va-loan/.
Ready to run the numbers on VA vs conventional for your situation?
Call or text Maureen Martin directly at (619) 857-7191.
Get pre-qualified in one conversation.
Frequently Asked Questions
1. Is a VA loan always better than a conventional loan for veterans?
Not always. For most VA-eligible buyers purchasing a primary residence with limited upfront cash, the VA loan provides structural advantages that are hard to match. Conventional can be the better fit for buyers with substantial savings, for investment properties, or for properties that would not pass a VA appraisal.
2. Can I use a VA loan and a conventional loan at the same time?
Yes, in some circumstances. VA-eligible buyers can hold a VA loan on a primary residence and a conventional loan on an investment or second property. In some situations, you can hold two active VA loans simultaneously with sufficient remaining entitlement.
3. Does the VA funding fee make the VA loan more expensive than conventional?
Not for most buyers with limited upfront cash. The funding fee is a one-time cost, while PMI is a monthly charge that continues for years. For most buyers holding the loan three or more years, the VA structure is generally less expensive than conventional with PMI. A lender can run the specific comparison for your situation.
4. Can a veteran choose conventional over VA if they prefer it?
Yes. VA eligibility does not require you to use a VA loan. Some buyers choose conventional to avoid the VA appraisal process, to purchase a property that would not meet VA MPRs, or because they have substantial savings and prefer to avoid the funding fee.
5. What is the VA conforming loan limit in San Diego for 2026?
The 2026 conforming loan limit for San Diego County is $1,104,000, per the FHFA. VA-eligible buyers with full entitlement face no county cap and may finance above that limit with significant upfront cost advantages, subject to lender underwriting and qualification requirements. Buyers with partial entitlement may have a cap based on remaining entitlement.
Maureen Martin
Maureen Martin is a San Diego mortgage broker with 26 years of experience specializing in VA loans and purchase loans. She is an independent broker affiliated with HomePlus Mortgage, serving military families and homebuyers across San Diego County.
NMLS# 247664
(619) 857-7191
Disclaimer: This content is for educational purposes only and does not constitute financial, legal, or mortgage advice. Loan eligibility, rates, terms, and program availability are subject to lender underwriting guidelines and may change without notice. All loans are subject to credit approval, income verification, and lender review.
Maureen Martin | CA DRE Lic. No. 01266511 | NMLS# 247664 HomePlus Mortgage | CA DRE Lic. No. 01021315 | NMLS# 78669
