Table of Contents
- Do you qualify for a VA loan in San Diego?
- Step 1: Get your Certificate of Eligibility (COE)
- Step 2: Get pre-approved with a San Diego VA lender
- Step 3: Find a VA-eligible property
- Step 4: VA appraisal and underwriting
- Step 5: Close on your San Diego home
- Documents you need to apply
- Real scenario: PCSing to San Diego
- Frequently asked questions
Key Takeaways
- Applying for a VA loan in San Diego takes five steps and typically closes in 30 to 45 days.
- You need a Certificate of Eligibility (COE) before you can apply. Maureen can pull it for you in minutes.
- Active duty service members can qualify after 90 consecutive days of service. You do not need to be separated or retired.
- The VA loan benefit offers significant upfront cost advantages and has no private mortgage insurance for eligible buyers with full entitlement, subject to lender underwriting and qualification requirements.
- Maureen works to move quickly on complete applications, subject to receipt of required documentation and lender review. Starting before your PCS orders arrive puts you ahead.
- The VA funding fee varies based on loan type and other factors. If you have a service-connected disability rating, you may be fully exempt.
Applying for a VA loan in San Diego takes five steps and closes in 30 to 45 days when your file is complete. That is the short answer. This guide walks through each step clearly so you know what to expect, what to gather, and when to start.
Maureen Martin is a San Diego mortgage broker with 26 years of experience specializing in VA loans and purchase loans. She has helped hundreds of military families and veterans apply for VA loans across San Diego County. If you are active duty, a veteran, or a qualifying surviving spouse, this is what the process looks like in 2026.
According to VA home loan county volume data published by the Veterans Benefits Administration, San Diego County consistently ranks among the highest-volume VA loan counties in the United States. That is no surprise: with four major military installations and one of the most expensive housing markets in the country, the VA loan benefit is used here every single month by families at every base.
Do You Qualify for a VA Loan in San Diego?
Before you apply, confirm that you meet the VA’s service requirements. The VA sets eligibility based on your service history and duty status.
Active duty service members
You qualify after 90 consecutive days of active service. Your lender will need a Statement of Service signed by your commanding officer or personnel office.
Veterans
Requirements vary based on when you served. Generally: 90 consecutive days of active service during wartime, or 181 days during peacetime. Veterans who enlisted after September 7, 1980 must have served 24 months or the full period called to active duty.
National Guard and Reserve members
You qualify with six creditable years of service, or 90 days of active duty under Title 10 or Title 32 orders (at least 30 consecutive days). The Veteran Health Care and Benefits Improvement Act of 2020 expanded eligibility for Title 32 activations.
Surviving spouses
Unremarried surviving spouses of service members who died in the line of duty or from a service-connected disability may qualify. Check current requirements directly on the VA’s eligibility page.
Other requirements
- Honorable or qualifying discharge. Dishonorable, bad conduct, and other than honorable discharges generally disqualify you, though some exceptions apply depending on the circumstances of discharge.
- Primary residence only. VA loans cannot be used for investment properties or vacation homes.
- No VA minimum credit score, but most lenders including Maureen require a 620 or above.
Not sure if you qualify? Maureen can check quickly. Visit sandiegohomelender.com/qualify-va-loan/ or call (619) 857-7191.
Step 1: Get Your Certificate of Eligibility (COE)
Your Certificate of Eligibility (COE) is the official VA document that confirms you are eligible for the VA loan benefit. Your lender needs it before they can process your loan.
There are three ways to get your COE:
- Through your lender (fastest): Maureen can pull your COE directly through the VA’s online system, usually in minutes. Most buyers do not need to request it themselves.
- Online via VA.gov: You can request your COE through the VA’s eBenefits portal at va.gov/housing-assistance/home-loans/how-to-request-coe/.
- By mail: Fill out VA Form 26-1880 and mail it to your regional loan center. This method takes significantly longer and is not recommended if you are on a PCS timeline.
What you need for your COE depends on your service status. Veterans need their DD-214. Active duty members need a Statement of Service. Guard and Reserve members need discharge documents or a points statement.
Step 2: Get Pre-Approved with a San Diego VA Lender
Pre-approval is the most important step before you start looking at homes. It tells you how much you can borrow, and it shows sellers you are a serious buyer with verified financing.
In San Diego’s competitive market, having a pre-approval letter in hand before you start touring gives you a real advantage when making offers.
What Maureen reviews during pre-approval:
- Your income, including base pay and BAH (which she grosses up by 25% as non-taxable income)
- Your debts and monthly obligations
- Your credit profile
- Your COE and VA entitlement status
Maureen offers free, no-obligation pre-approval. She works to move quickly on complete applications, subject to receipt of required documentation and lender review. For a full overview of the VA loan benefit before you apply, visit Maureen’s VA loan page.
Step 3: Find a VA-Eligible Property in San Diego
VA loans are for primary residences only. You cannot use a VA loan to buy an investment property, a vacation home, or a property you do not plan to live in.
The property must also meet the VA’s Minimum Property Requirements (MPRs), which confirm the home is safe, sound, and structurally livable. Most standard single-family homes in San Diego meet these requirements without any issues.
The main exception to watch for is condos. A condo must be on the VA’s approved list before you can finance it with a VA loan. Not all condo projects in San Diego qualify.
- Avoid condos in Del Mar, Solana Beach, downtown San Diego, and Mission Valley. These areas have many VA-ineligible projects.
- Before touring any condo, ask Maureen to check its VA approval status. It takes a few minutes and can save you from wasting time on a property that will not qualify.
Step 4: VA Appraisal and Underwriting
Once your offer is accepted, the VA requires an appraisal of the property. This is not the same as a home inspection. The VA appraisal does two things: it confirms the home meets the MPRs, and it establishes a market value for the property.
If the appraisal comes in below the purchase price, you have three options: negotiate the price down, pay the difference out of pocket, or walk away using the VA’s Escape Clause. Maureen walks buyers through this scenario before they make an offer so there are no surprises.
While the appraisal is underway, your full loan file goes to underwriting. The underwriter reviews your COE, income documentation, appraisal, and title work to issue final loan approval.
Step 5: Close on Your San Diego Home
VA loans typically close in 30 to 45 days with a responsive buyer and a complete file. Responding quickly to lender requests is the single biggest factor in keeping your timeline on track.
At least three days before closing, you will receive a Closing Disclosure outlining your final loan terms and all closing costs including the VA funding fee. Review it carefully and ask Maureen about anything that does not look right.
The VA funding fee varies based on your loan type and whether this is your first use of the benefit. It can be rolled into your loan. If you have a service-connected disability rating, you may be fully exempt. Always confirm your exemption status with Maureen before you close.
What Documents Do You Need to Apply for a VA Loan in San Diego?
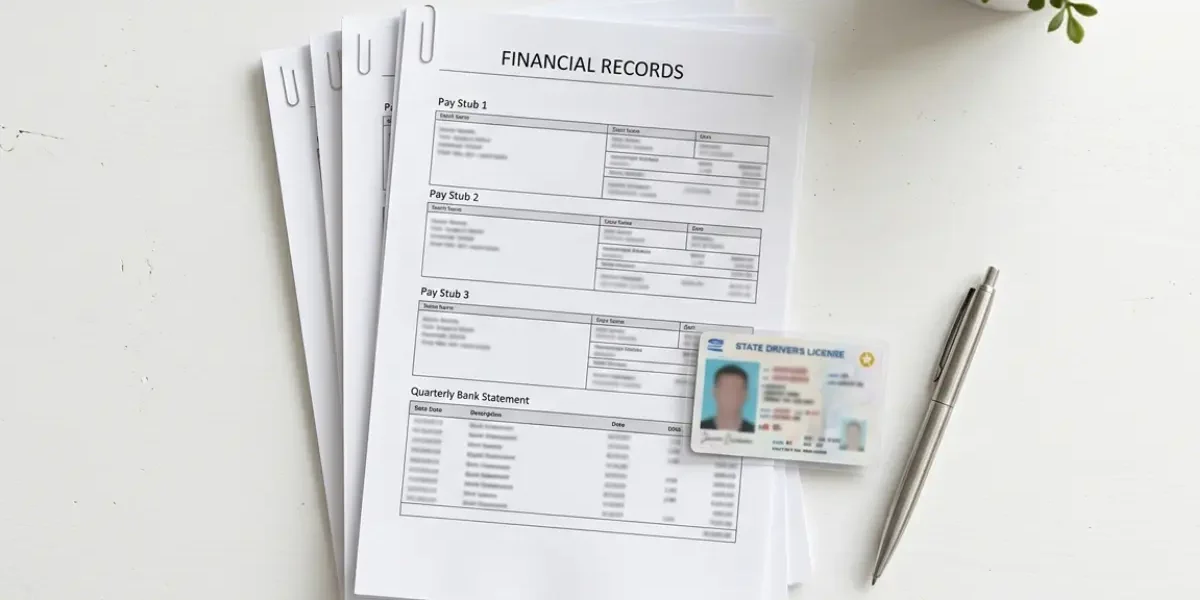
- DD-214 (veterans) or Statement of Service signed by your commanding officer (active duty)
- Certificate of Eligibility (Maureen can pull this for you)
- Last two years of W-2s or federal tax returns
- Most recent 30 days of pay stubs
- Last two months of bank statements
- PCS orders (if you are relocating to San Diego)
- Government-issued photo ID
Self-employed borrowers and those with non-standard income may need additional documentation. Maureen will let you know exactly what is needed based on your situation.
Ready to apply for a VA loan in San Diego?
Call or text Maureen Martin directly at (619) 857-7191.
Get pre-qualified in one conversation.
Frequently Asked Questions
1. How long does it take to apply for a VA loan in San Diego?
The full process from pre-approval to closing typically takes 30 to 45 days with a complete file. Maureen works to move quickly on complete applications, subject to receipt of required documentation and lender review. Starting the process before your PCS orders arrive puts you in the strongest position.
2. Can I apply for a VA loan before I have my PCS orders?
Yes. Maureen can begin the pre-approval process before your orders arrive. She can pull your COE, review your income, and issue a pre-approval letter so you are ready to make offers the moment you need to. Orders will be required before closing but not before pre-approval.
3. Does Maureen help with the COE process?
Yes. Maureen can pull your Certificate of Eligibility directly through the VA’s online system, usually within minutes. Most buyers do not need to request it themselves. If there are any complications with your COE, Maureen handles that too.
4. What credit score do I need to apply for a VA loan in San Diego?
The VA itself does not set a minimum credit score. Maureen generally works with buyers at 620 and above. If your score is below that, she can walk you through practical steps to improve it before applying.
5. Can I apply for a VA loan if I still have one on another property?
Yes, in most cases. If you have remaining entitlement, you can use a second VA loan without selling your first property. If your entitlement is partially used, you may still qualify with a smaller guarantee. Maureen can calculate your remaining entitlement in one phone call.
Maureen Martin
Maureen Martin is a San Diego mortgage broker with 26 years of experience specializing in VA loans and purchase loans. She is an independent broker affiliated with HomePlus Mortgage, serving military families and homebuyers across San Diego County.
NMLS# 247664
(619) 857-7191
Disclaimer: This content is for educational purposes only and does not constitute financial, legal, or mortgage advice. Loan eligibility, rates, terms, and program availability are subject to lender underwriting guidelines and may change without notice. All loans are subject to credit approval, income verification, and lender review.
Maureen Martin | CA DRE Lic. No. 01266511 | NMLS# 247664 HomePlus Mortgage | CA DRE Lic. No. 01021315 | NMLS# 78669
