Table of Contents
- Myth 1: You need perfect credit to get a VA loan
- Myth 2: VA loans have large upfront costs
- Myth 3: VA loans take longer to close than conventional loans
- Myth 4: You can only use a VA loan once
- Myth 5: Active duty and deployed service members do not qualify
- Myth 6: Sellers should avoid VA loan buyers
- Myth 7: You cannot buy a condo with a VA loan in San Diego
- Frequently asked questions
Key Takeaways
- The VA sets no minimum credit score. Lenders apply their own standards, but VA loans are generally more flexible than conventional loans on credit history.
- The VA loan benefit offers significant upfront cost advantages and has no PMI for eligible buyers with full entitlement, subject to lender underwriting and qualification requirements.
- VA loans close in 30 to 45 days in 2026, comparable to conventional loan timelines. The myth that VA loans are slow is outdated.
- The VA loan benefit is reusable for life. You can have more than one active VA loan at the same time under the right circumstances.
- Active duty service members qualify after 90 consecutive days of service. Deployed members can apply through a Power of Attorney.
- VA loans have historically maintained among the lowest foreclosure rates of any mortgage type, according to VA program data. They are not risky for sellers.
- You can buy a condo with a VA loan in San Diego, but only if the project is on the VA’s approved list. Always check before you tour.
VA loan myths are not just harmless misconceptions. They cost San Diego military families real money and real homebuying opportunities every year. A buyer who thinks they need perfect credit never calls a lender. A buyer who thinks VA loans are bad for sellers removes their own offer from consideration before they even start.
According to the U.S. Department of Veterans Affairs, the vast majority of VA-backed home loans are made with significant upfront cost advantages for eligible buyers. The program works. It has worked for decades. What gets in the way are the myths. Here are seven of the most common ones, busted.
Myth 1: You Need Perfect Credit to Get a VA Loan
Myth: You need a high credit score to qualify for a VA loan.
Fact: The VA sets no minimum credit score requirement. What the VA asks for is that a borrower be a satisfactory credit risk: a judgment that considers the full picture of your financial history, not just a single number.
Lenders apply their own credit standards on top of the VA’s guidelines, and those standards vary. VA loans are generally more flexible on credit history than conventional loans, which is one of the reasons the program serves a broader population of buyers. A past bankruptcy, a period of financial hardship, or a lower score does not automatically disqualify you.
If you are unsure where your credit stands, the best first step is a conversation with a lender before you assume the answer is no.
For the official VA eligibility requirements, visit va.gov/housing-assistance/home-loans/eligibility/.
Myth 2: VA Loans Have Large Upfront Costs
Myth: You need a lot of cash upfront to buy a home with a VA loan.
Fact: The VA loan benefit offers significant upfront cost advantages for eligible buyers with full VA entitlement, subject to lender underwriting and qualification requirements. There is no county-level loan cap for full entitlement buyers, which means the benefit applies regardless of the purchase price.
In San Diego, where median home prices are approaching $900,000, this is one of the most powerful aspects of the VA loan program. A buyer without VA eligibility purchasing at that price point would need a significant cash outlay just to make the numbers work. Many VA-eligible buyers with full entitlement face much lower upfront barriers.
This benefit has been in place since 2020 when Congress eliminated the county-level loan limits for full entitlement buyers. If you have previously used your VA loan benefit and still have an active VA loan, your remaining entitlement may affect your benefits. Verify your entitlement status with your lender before assuming the full benefit applies.
Myth 3: VA Loans Take Longer to Close Than Conventional Loans
Myth: VA loans are slow and sellers should expect delays.
Fact: VA loans are competitive with conventional loans on closing timelines. In 2026, most VA loans close in 30 to 45 days, comparable to a standard conventional loan. The myth that VA loans are slow is outdated.
This myth persists because VA loans require a VA appraisal, which some buyers and sellers assume adds weeks to the process. In practice, VA loan processing has become increasingly automated and efficient. In 2026, most VA loans close in 30 to 45 days, comparable to conventional loan timelines. The gap between VA and conventional closing times has narrowed significantly as lenders experienced with VA loans have streamlined the process.
The biggest variable in any loan timeline (VA or conventional) is how quickly the buyer responds to lender document requests. A prepared buyer with a complete file will close faster than an unprepared buyer with any loan type.
Myth 4: You Can Only Use a VA Loan Once
Myth: The VA loan benefit is a one-time-only program.
Fact: The VA loan is a lifetime benefit. You can use it multiple times, and in some circumstances you can have more than one active VA loan at the same time.
Your VA loan entitlement is restored when you pay off a VA loan and sell the home, or when you pay off the loan and request a one-time restoration while keeping the home. If you have remaining or restored entitlement, you can use it again.
Many San Diego military families use their VA loan benefit at every duty station. A sailor who bought a home near Naval Base San Diego, sold it, and later returned to San Diego can use their VA benefit again. The program is designed for a military lifestyle that involves multiple moves over a career.
To check your current entitlement status, visit Maureen’s VA loan page or call (619) 857-7191.
Myth 5: Active Duty and Deployed Service Members Do Not Qualify
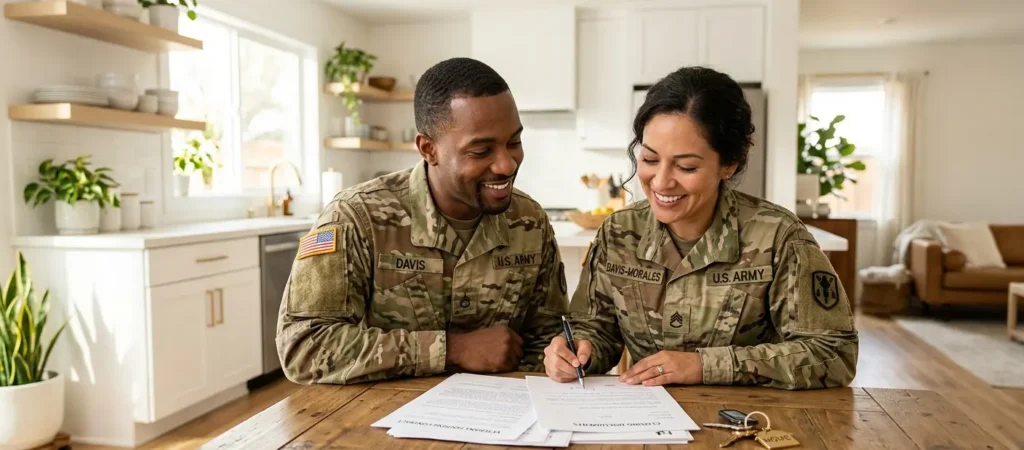
Myth: VA loans are only for veterans who have left the military.
Fact: Active duty service members qualify for VA loans after 90 consecutive days of service. You do not need to be separated or retired to use your benefit.
This is one of the most consequential myths because it stops active duty buyers from using a benefit they have already earned. Service members stationed at Camp Pendleton, Naval Base San Diego, MCAS Miramar, and NAS North Island qualify while they are still in uniform.
For deployed service members who cannot be physically present for the purchase, a Power of Attorney allows a designated person, often a spouse, to act on their behalf throughout the process. Remote pre-approvals, digital document signing, and video tours make it possible for deployed buyers to complete a purchase without being in San Diego.
Myth 6: Sellers Should Avoid VA Loan Buyers
Myth: Accepting a VA loan offer means more risk and more hassle for the seller.
Fact: VA loans have had among the lowest foreclosure rates of any mortgage type for most of the past decade. A pre-approved VA buyer is a well-qualified buyer.
The myth that VA loans are problematic for sellers persists in some real estate circles, but the data does not support it. The VA loan program has strict appraisal and underwriting standards that protect both the buyer and the seller. A VA appraisal confirms market value and property condition. This benefits the seller as much as the buyer.
In San Diego’s military-heavy market, refusing VA loan offers means turning away a large portion of the most motivated and financially stable buyers in the county. For sellers near the bases (Chula Vista, National City, Mira Mesa, Oceanside, or Carlsbad), a VA offer from a pre-approved military buyer is often the strongest offer on the table.
Myth 7: You Cannot Buy a Condo with a VA Loan in San Diego
Myth: You cannot use a VA loan to buy a condo.
Fact: You can use a VA loan to buy a condo in San Diego, but only if the condo project is on the VA’s approved list. The approval applies to the entire project, not individual units.
This myth is half true, which makes it particularly dangerous. VA loans are available for condos, but only in projects that have been reviewed and approved by the VA. Not all San Diego condos qualify. A buyer who assumes any condo is fair game may fall in love with a unit and make an offer before discovering the project is not on the VA list.
You can check any project’s VA approval status at lgy.va.gov/lgyhub/condo-report. The check takes about five minutes. Always do it before you tour, not after you fall in love with a unit.
Since 2019, the VA also allows Single Unit Approval (SUA), which can allow VA financing on individual units even when the full project is not on the approved list. SUA adds time to the process but opens up additional inventory for VA buyers in San Diego.
To check if you qualify for a VA loan in San Diego, visit sandiegohomelender.com/qualify-va-loan/.
Ready to use your VA benefit in San Diego? Let's talk.
Call or text Maureen Martin directly at (619) 857-7191.
Get pre-qualified in one conversation.
Frequently Asked Questions
1. Does the VA loan benefit offer significant upfront cost advantages?
Yes, for buyers with full VA entitlement, subject to lender underwriting and qualification requirements. There is no county-level loan cap for full entitlement buyers. If you have partial entitlement remaining from a previous VA loan, your capacity may be limited. Verify your entitlement status with your lender.
2. Can I get a VA loan if I had a bankruptcy or foreclosure?
Generally yes, after a waiting period. For a Chapter 7 bankruptcy, most lenders require a two-year waiting period from discharge. For a foreclosure, the typical waiting period is also two years. VA loans are more forgiving of past financial hardship than conventional loans.
3. Does the VA loan benefit expire?
No. Veterans and service members who earned eligibility decades ago can still use it today, as long as they meet current service and eligibility requirements.
4. Can I use a VA loan if I am currently deployed overseas?
Yes. A Power of Attorney allows a designated person to act on your behalf throughout the purchase process. Remote pre-approvals, digital document signing, and video tours make it possible for deployed buyers to complete a purchase without being physically present in San Diego.
5. Are VA loans only available for single-family homes?
No. VA loans can be used for single-family homes, townhomes, condos (in VA-approved projects), and multi-unit properties up to four units, as long as the buyer occupies one unit as their primary residence.
Maureen Martin
Maureen Martin is a San Diego mortgage broker with 26 years of experience specializing in VA loans and purchase loans. She is an independent broker affiliated with HomePlus Mortgage, serving military families and homebuyers across San Diego County.
NMLS# 247664
(619) 857-7191
Disclaimer: This content is for educational purposes only and does not constitute financial, legal, or mortgage advice. Loan eligibility, rates, terms, and program availability are subject to lender underwriting guidelines and may change without notice. All loans are subject to credit approval, income verification, and lender review.
Maureen Martin | CA DRE Lic. No. 01266511 | NMLS# 247664 HomePlus Mortgage | CA DRE Lic. No. 01021315 | NMLS# 78669
