San Diego Mortgage Broker & VA Loan Specialist
Your Best Friend in The Mortgage Industry
Honest Answers, Guidance Toward a Smooth Closing
“An amazing person to work with. Plans ahead for any hiccups in the process and is very organized. Definitely recommend her to anyone looking to purchase or refi a home!”
Christian T.
San Diego's VA & Purchase Loan Specialist for 26+ Years
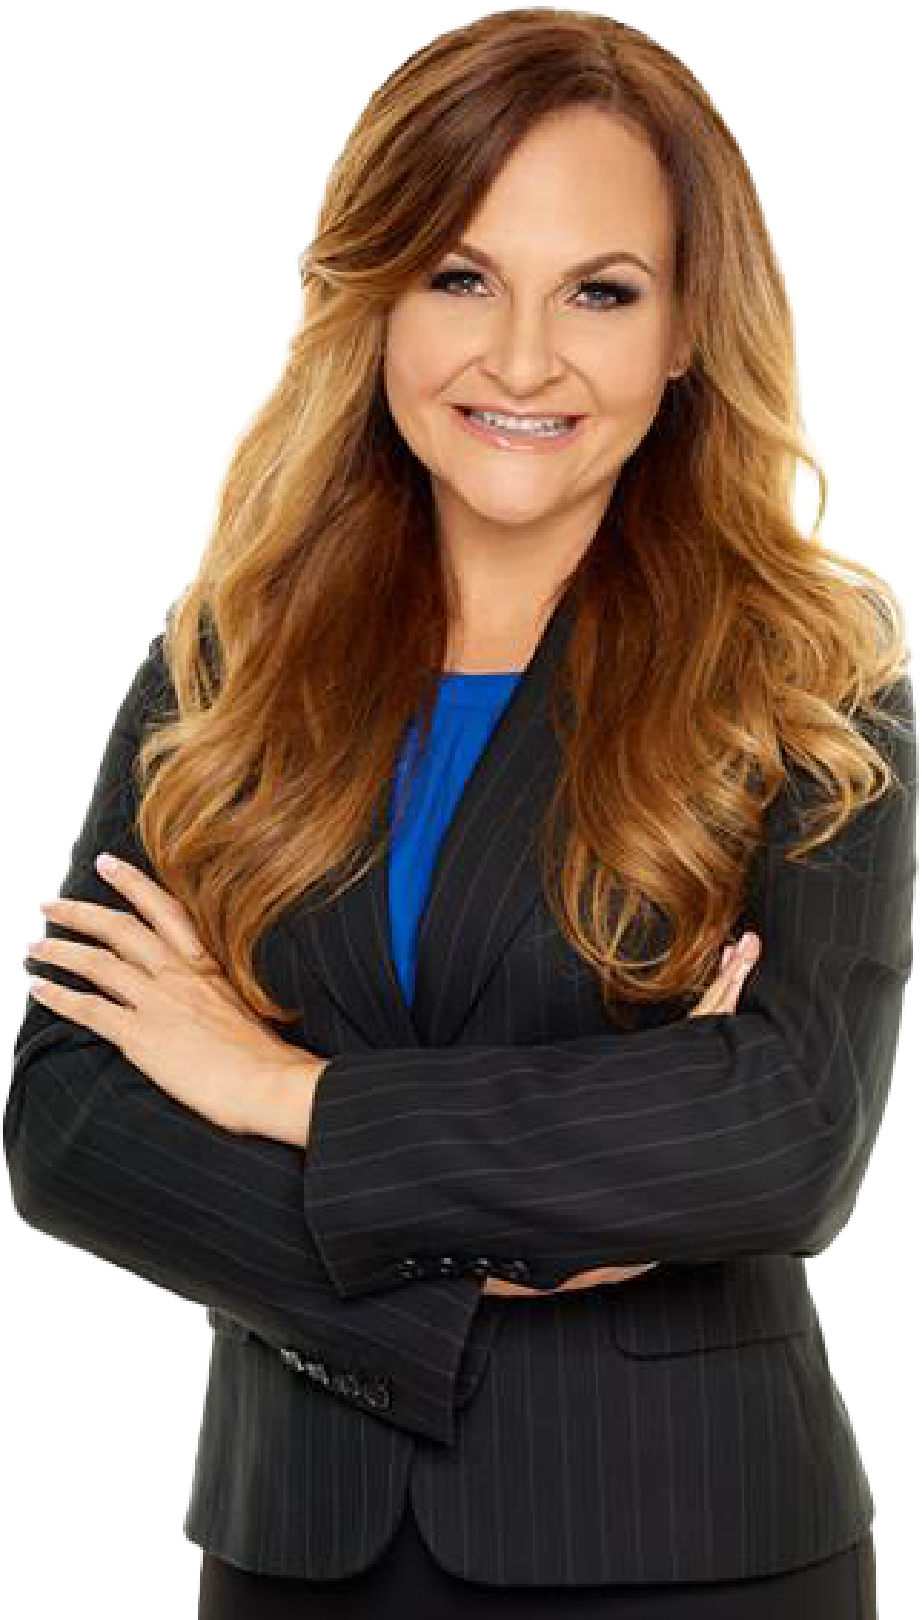
Maureen Martin is a mortgage loan officer at HomePlus Mortgage and has more than 26 years of experience in the San Diego, CA mortgage lending market. NMLS #247664.
For 26+ years I’ve helped San Diego families buy homes and use their VA benefits the way they’re meant to be used. No call centers. No rate-shopping games. Clear communication about closing costs and loan terms. Just real mortgage guidance from someone who has been doing this since the late nineties.
I’m Maureen Martin, an independent mortgage broker right here in San Diego. My job is to be your best friend in the mortgage industry, which means I answer when you call, I explain what’s actually happening, and I’ll tell you straight when a deal isn’t right, even if it costs me the loan.
Here’s what makes working with me different. I run my business solo with one trusted processor. I’m not a direct lender pushing one product line. I’m a broker shopping your loan across multiple wholesale lenders so you get options instead of a single bank’s pricing. When you call my number, you get me, not a junior officer reading a script.
My office is in Mission Valley at 1455 Frazee Road, and I meet clients in person anywhere in San Diego County or by phone, whichever is easier for you.
As Featured on Good Business San Diego
VA Loans for San Diego Military Families
San Diego is one of the biggest VA loan markets in the country. Between Camp Pendleton, Naval Base San Diego, MCAS Miramar, and NAS North Island, military families move in and out of this city every single month. I’ve spent more than two decades helping them get into homes using their VA entitlement the right way.
Eligible borrowers with full VA entitlement may qualify for zero down payment, subject to lender approval, property appraisal, and other requirements. VA loans do not require monthly mortgage insurance; a VA funding fee may apply unless the borrower is exempt. VA does not impose a county loan limit for borrowers with full entitlement, although lenders may impose their own limits. Interest rates and closing costs are subject to change based on market conditions, borrower qualifications, and lender guidelines.
If you’re stationed at one of San Diego’s military bases or PCS’ing here from somewhere else, here’s where I help most often:
- Camp Pendleton Marines and families buying in Oceanside, Carlsbad, Vista, San Marcos, Fallbrook, and Bonsall
- Naval Base San Diego sailors buying in Chula Vista, Bonita, Imperial Beach, National City, and South Bay
- NAS North Island sailors buying in Coronado and Coronado Cays (where VA jumbo loans are a regular conversation)
- MCAS Miramar Marines buying in Mira Mesa, Scripps Ranch, Poway, Rancho Bernardo, and Carmel Mountain
Already own a home with a VA loan? I also help San Diego veterans with VA refinances, including the VA IRRRL (streamline) to lower your rate and the VA cash-out refinance to access equity or move an FHA or conventional loan into a VA loan.
Purchase Loans Across San Diego County
Buying a home in San Diego is a big deal, and it should feel that way. I focus mainly on VA Home Loans and purchase loans, which means I’m focused on the people who are actually buying houses. First-time buyers, move-up buyers, and Active Duty Military or Veterans moving to San Diego from out of state.
Whether you’re putting 3% down on a starter condo or 20% down on a single-family home in Coronado, I’ll match you with a loan that actually fits the property and your plan.
First time home buyer in San Diego? You likely don’t need 20% down. FHA and conventional programs allow much lower down payments. With many conventional loans, private mortgage insurance (PMI) may be cancellable by your servicing company when applicable requirements are met.
Understanding the Loan Process
3 Simple Steps to Pre-Approval. Pre-approval can be valuable in a competitive California market but is not a guarantee of final loan approval.
1.
Schedule A FREE
Consultation
2.
Mortgage Plan
3.
Request a free, no-obligation mortgage pre-approval.
Typical turnaround time is 24–48 business hours (excluding weekends and holidays), once all required documentation has been received and reviewed. Timing may vary based on individual circumstances and lender requirements.
What you’ll need for a mortgage pre-approval: recent pay stubs, W-2s or tax returns, two months of bank statements, and a photo ID. Self-employed borrowers may need additional documents. Avoid opening new credit while you shop, and I’ll tell you exactly what applies to your situation.
A Different Way to Work with a Mortgage Broker
Most lenders in San Diego fall into one of two buckets. There’s the big national crowd (Rocket, SoFi, Veterans United), where you’re a file number and a portal login. And there’s the local direct-lender shops with a team of loan officers where you might get one person on Tuesday and someone else on Thursday.
I’m neither. I’m a solo broker. When you call my number, you get me. When something gets weird with underwriting, I’m the one calling you back, not a bot. And because I’m a broker (not a direct lender), I’m not stuck selling one bank’s product. I shop your loan across more than multiple wholesale lenders and find the one that actually fits your situation.
That’s how I’ve run my business for 26+ years, and it’s why most of my work today still comes from past clients and the people they send my way.
- Conventional Loans
- VA Loans
- VA IRRRL's
- FHA Loans
- First Time Homebuyers
- Reverse Mortgage Loans
Learn From Our Experience
Try Our New Mortgage Calculator
See What Our Clients Are Saying About Us!
Finding Out if You Prequalify is Easy
Contact Maureen Martin Today at (619) 857-7191 or click the button below to fill out a contact form.
Top Rated Mortgage Loan Officer
Maureen Martin with HomePlus Mortgage is a trusted San Diego mortgage broker serving the greater San Diego area. Whether you prefer an in-person consultation or a convenient phone call, Maureen is ready to meet with you at your preferred location or discuss your mortgage needs over the phone.
Schedule an appointment today to get personalized answers to all your mortgage questions and expert guidance throughout your home financing journey.
Maureen Martin with HomePlus Mortgage is a trusted mortgage lender serving the greater San Diego area. Whether you prefer an in-person consultation or a convenient phone call, Maureen is ready to meet with you at your preferred location or discuss your mortgage needs over the phone.
We are open Monday – Friday 8:00am-6:00pm | Weekends by appointment.
Frequently Asked Questions
How long has Maureen Martin been a mortgage broker in San Diego?
What kinds of loans does Maureen specialize in?
Is Maureen a mortgage broker or a direct lender?
I’m an independent mortgage broker. That means I shop your loan to more than 75+ wholesale lenders to find the rate and program that actually fits your situation. Direct lenders are stuck selling their own product line. As a broker, I’m not. You get options instead of a single bank’s pricing.
What is the 2026 VA loan limit in San Diego County?
In 2026, if you have full VA entitlement, you can borrow up to that amount with zero down. If your entitlement is partial, the math gets more involved, and that’s a conversation worth having before you make an offer.
What parts of San Diego does Maureen serve?
All of San Diego County. That includes Camp Pendleton, Naval Base San Diego, MCAS Miramar, NAS North Island, and the surrounding communities. Oceanside, Carlsbad, Vista, San Marcos, Escondido, Poway, La Jolla, Mission Hills, Chula Vista, Bonita, National City, Imperial Beach, La Mesa, El Cajon, Santee, Lakeside, Coronado, and inland to East County.
How fast can Maureen close a loan in San Diego?
Most of my loans close in 21 to 30 days. I’ve closed VA loans in under 17 days when a competitive offer required it. The timeline depends on the appraisal queue and how quickly we get docs in. Tighter timelines are doable with planning.
How do I get started?
Two options. Call me directly to talk through your situation in real conversation, or fill out the pre-qualification form and I’ll review it personally before I call back. Either way, you’re talking to me, not a queue.